Prices as of April 23, 2026. Tangible equity is from Banner's most recent 10-K at the time; shares outstanding are from Yahoo Finance.
Method and full write-up for the Banner takeover cross-check
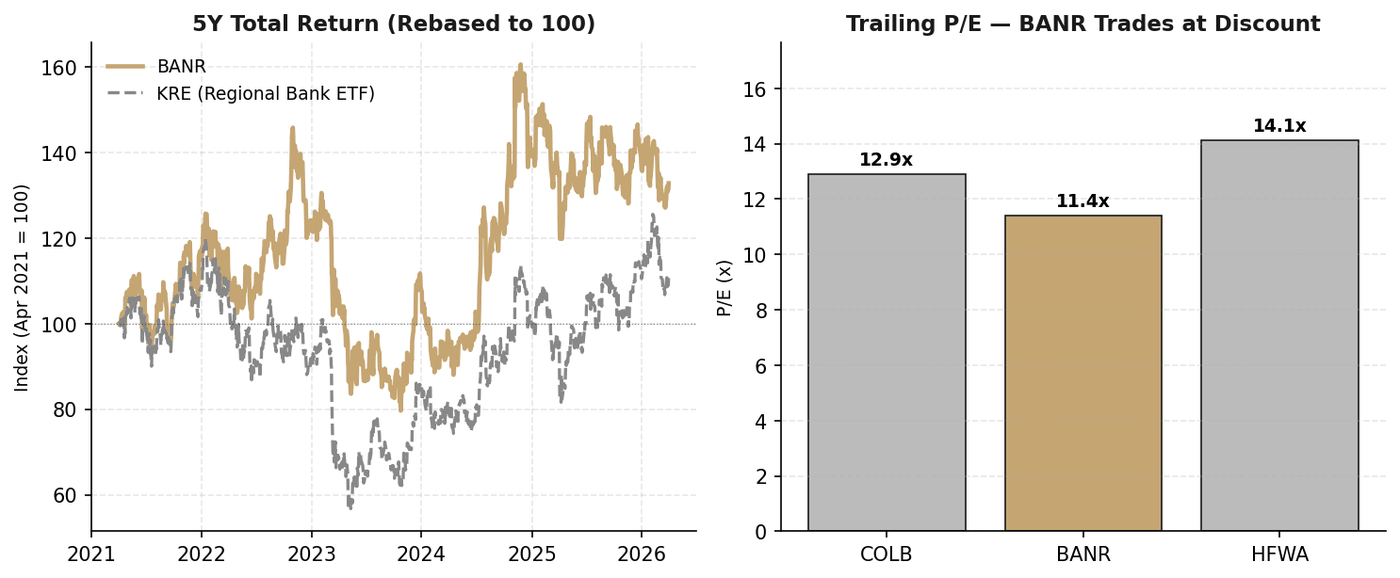
Why this exists: The BANR pitch reaches its $82.02 target with peer P/E, normalized P/E, and price-to-book. This memo asks a different question: what would a strategic acquirer plausibly pay? Price to tangible book value (P/TBV) is the standard bank-M&A yardstick, so it tests the target from a franchise-value angle instead of an earnings angle.
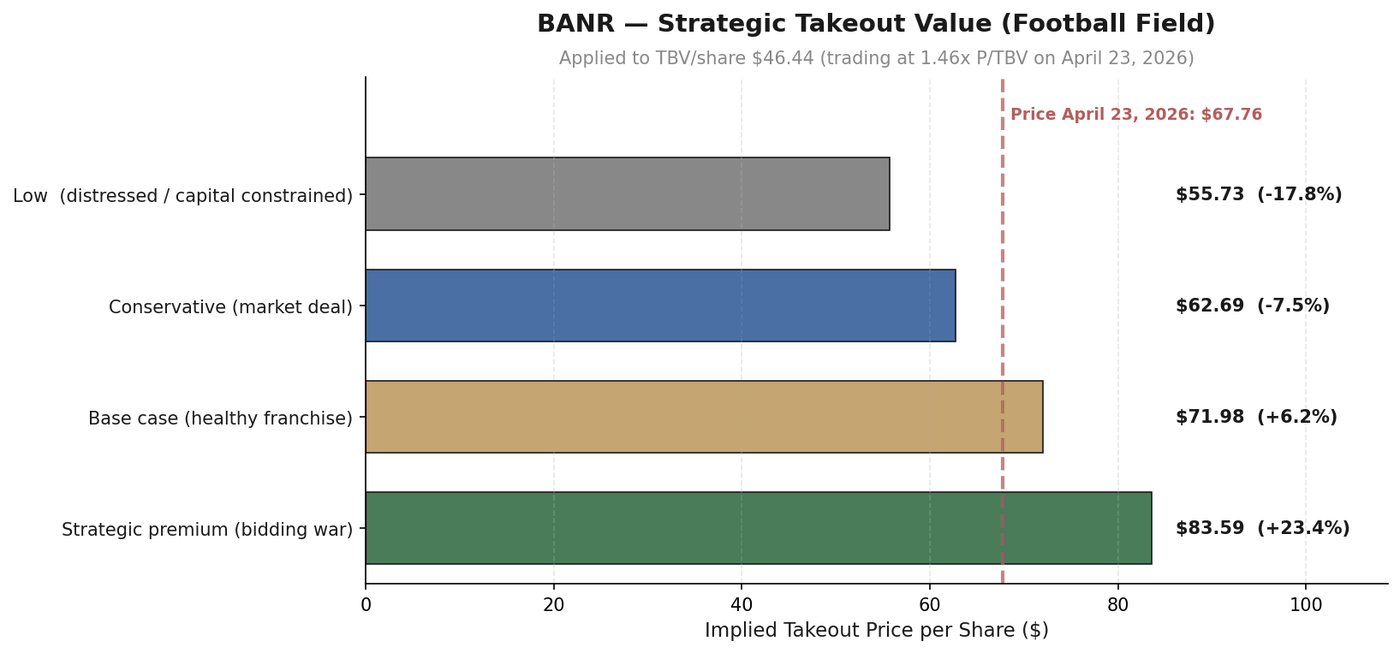
Finding, convergence rather than extra upside: BANR already trades at 1.46× P/TBV, above the routine-deal multiple used here (1.35×), so the market already prices in some takeover value. The base-case takeout of $71.98 is below the $82.02 standalone target. Only the strategic-premium scenario ($83.59) lines up with the long thesis. Takeaway: a takeover is optionality, not extra upside on top of the pitch.
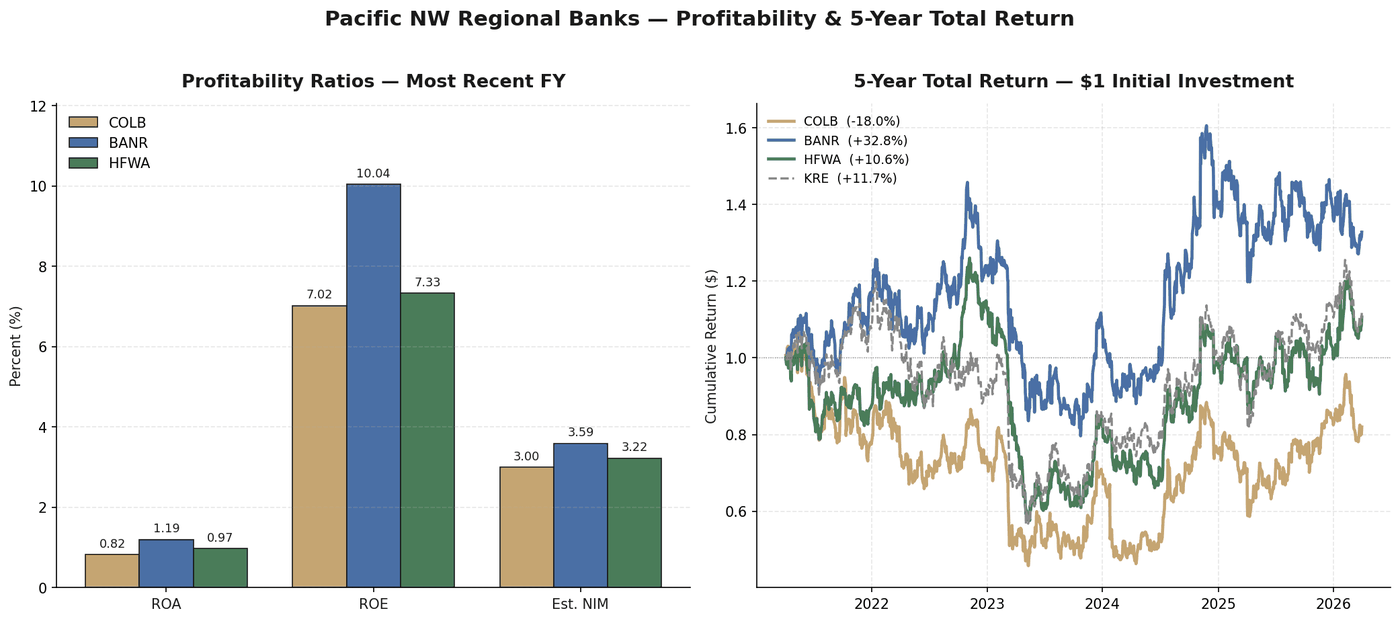
Why BANR could be a target: (1) Size: $16.4B in assets, large enough to matter and small enough for a regional acquirer to absorb. (2) Franchise: a Washington, Oregon, California, and Idaho community-banking footprint that would be hard to replicate quickly. (3) Profitability: 10.04% ROE and 1.19% ROA, the highest of the three Pacific Northwest peers in the comparison. (4) Capital: equity/assets of 11.9%.
Plausible acquirers (illustrative): GBCI (Glacier Bancorp: Mountain West and Northwest community-bank focus, grows through acquisitions), ZION (Zions: western regional with a relatively small Oregon/Washington presence), FIBK (First Interstate: recent Great Western acquisition), and WAFD (WaFd Bank: recent Luther Burbank acquisition, neighboring footprint). None reflects any actual or reported interest.
Approach: BANR fundamentals come from SEC EDGAR XBRL, using the same code as the Pacific Northwest bank comparison. Goodwill ($373M) is subtracted from equity to get tangible equity, which is divided by shares outstanding for TBV per share. Banner's $1.5M of other intangibles was not deducted (about $0.04 per share). The four P/TBV scenarios (1.20×, 1.35×, 1.55×, 1.80×) are general industry ranges for community-bank deals, not multiples from specific comparable transactions. Outputs: a football-field chart (matplotlib), a three-sheet workbook (summary, acquirers, methodology), and a two-page deal memo PDF (ReportLab).
Caveats: This is a framework exercise, not a deal prediction; no transaction is announced or rumored. Bank Holding Company Act control rules make private-equity buyouts of banks rare, which is why it looks only at bank acquirers. Acquirer accretion/dilution is not modeled; that would require the acquirer's financials, purchase accounting, synergies, and financing mix.
Built with: Python (matplotlib, ReportLab), SEC EDGAR XBRL API